Building a thriving side hustle, freelancing business, or solo enterprise gives you freedom, control, and unlimited earning potential. However, it also strips away a major corporate perk: the employer-sponsored 401(k) match. When you work for yourself, setting up your own safety net falls entirely on your shoulders.
Fortunately, the U.S. tax code offers powerful tax-advantaged accounts designed specifically for self-employed individuals and side hustlers. The two most popular and effective options are the Solo 401(k) and the Simplified Employee Pension (SEP) IRA. Both let you save significantly more for retirement than a traditional or Roth IRA while reducing your current year’s taxable income.
Choosing between a Solo 401(k) or SEP IRA can alter your tax trajectory, your savings speed, and your administrative workload. In my work with self-employed clients, I’ve found that the “best” account rarely comes down to total contribution limits alone—it depends on your side hustle income level, whether you have a W-2 day job, and how much administrative oversight you’re willing to handle.
In this comprehensive guide, we’ll break down the Solo 401(k) vs SEP IRA debate for 2026. We will analyze contribution limits, administrative requirements, Roth features, loan options, and real-world income scenarios so you can select the best retirement plan for your side hustle.
Overview: Understanding the Basics
Before diving into the granular mechanics, let’s look at what each plan actually is and who it was designed to serve.
       +-------------------------------------------------------+
       |             SELF-EMPLOYED RETIREMENT PLANS            |
       +---------------------------+---------------------------+
                                   |
         +-------------------------+-------------------------+
         |                                                   |
         v                                                   v
+------------------+                               +------------------+
|   Solo 401(k)    |                               |     SEP IRA      |
+------------------+                               +------------------+
| * For business   |                               | * For solo pros  |
|   owners & solo  |                               |   & businesses   |
|   side hustlers  |                               |   WITH employees |
| * NO full-time   |                               | * Paperwork is   |
|   employees      |                               |   minimal        |
| * Dual roles:    |                               | * Employer-only  |
|   Employee +     |                               |   contributions  |
|   Employer       |                               |                  |
+------------------+                               +------------------+
What Is a Solo 401(k)?
A Solo 401(k)—also called an Individual 401(k) or One-Participant 401(k)—is a traditional 401(k) plan designed specifically for self-employed individuals and business owners who have no full-time employees other than themselves and an eligible spouse.
The magic of the Solo 401(k) lies in its dual-role structure. Because you are both the employer and the employee of your business, you can make retirement contributions in both capacities:
- As the Employee: You can contribute up to 100% of your earned self-employment income up to the annual elective deferral limit.
- As the Employer: You can make a profit-sharing contribution of up to 20% of your net self-employment income (or 25% of W-2 wages if incorporated as an S-Corp or C-Corp).
What Is a SEP IRA?
A SEP IRA (Simplified Employee Pension) is a traditional IRA variant that allows self-employed individuals and small business owners to make tax-deductible contributions into a retirement account for themselves and any eligible employees.
Unlike the Solo 401(k), a SEP IRA operates under an employer-only contribution framework. You cannot make elective “employee deferrals” into a standard SEP IRA. Every dollar contributed is categorized as an employer profit-sharing contribution. If you ever hire full-time employees in the future, you must contribute the exact same percentage of salary to their SEP IRAs as you do to your own.
Solo 401(k) vs SEP IRA: Key Structural Differences
To select the best self-employed retirement account comparison for your situation, you need to understand how these accounts function side by side across key categories.
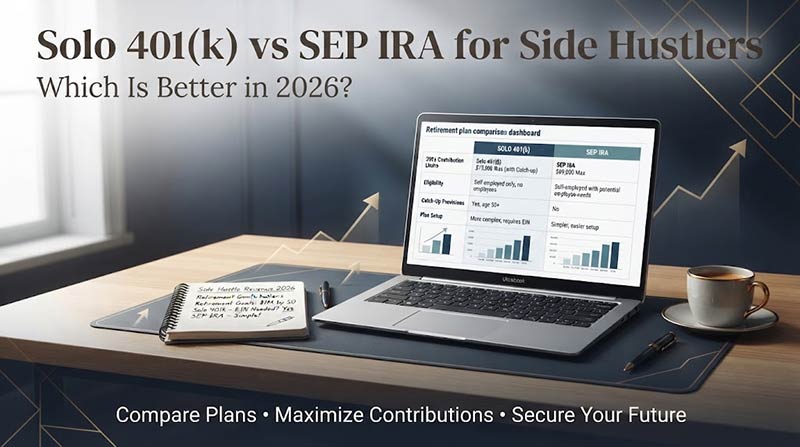
| Feature | Solo 401(k) | SEP IRA | Winner for Most Side Hustlers |
| 2026 Overall Contribution Cap | $70,000 (plus catch-up if 50+) | $70,000 | Tie (Maximum limits are equal) |
| Contribution Speed at Low Income | High (Up to $23,500 + profit share) | Low (Max ~20% of net profit) | Solo 401(k) |
| Roth Option Available? | Yes (Employee & Employer portions) | Yes (Designated Roth SEP) | Solo 401(k) (Easier provider support) |
| Loan Provision? | Yes (Up to 50% or $50,000) | No (Prohibited by law) | Solo 401(k) |
| Administrative Complexity | Moderate (Form 5500-EZ at $250k) | Very Low (No annual filing) | SEP IRA |
| Employee Eligibility | Spouse only | Must include eligible workers | Solo 401(k) (If keeping it solo) |
| Establishment Deadline | Dec 31 of tax year (or tax deadline) | Tax deadline + extensions | SEP IRA |
1. Contribution Mechanics & Speed
Both accounts share the same maximum total contribution limit set by the IRS ($70,000 for 2026). However, how fast you reach that limit differs dramatically.
With a SEP IRA, your contribution is capped at roughly 20% of your net self-employment income (net earnings after deducting half of your self-employment tax). If your side hustle makes $30,000 in net profit, your maximum SEP IRA contribution is approximately $6,000.
With a Solo 401(k), you can contribute 100% of your first $23,500 in net earned income as an employee deferral, plus another 20% of the remaining net earnings as an employer profit share. That same $30,000 side hustle profit allows you to contribute roughly $23,500 or more, shielding almost your entire side income from current taxation.
2. Roth Features
Tax diversification is a cornerstone of smart retirement planning. Having funds in both pre-tax and Roth (after-tax) accounts gives you flexibility when managing tax brackets in retirement.
- Solo 401(k): Most major brokers offer a Roth Solo 401(k) option at no extra charge. You can make your employee contribution ($23,500 in 2026) directly as a Roth contribution. Following recent SECURE 2.0 Act updates, employer matching and profit-sharing contributions can also be designated as Roth if your plan document permits.
- SEP IRA: While SECURE 2.0 authorized Roth SEP IRAs, custodian adoption remains limited. Many major brokerages still do not support Roth SEP IRAs or require additional manual tax reporting.
3. Account Loans
If you need liquidity to fund business operations, invest in real estate, or handle an emergency, a Solo 401(k) offers a built-in safety valve:
- Solo 401(k) Loans: You can borrow up to 50% of your total vested balance, up to a maximum of $50,000, without triggering taxes or early withdrawal penalties. You pay the interest back to yourself.
- SEP IRA Loans: IRAs do not allow loans. Taking money out of a SEP IRA before age 59½ generally triggers immediate income taxes plus a 10% early withdrawal penalty (unless an exception applies).
4. Setup Deadlines & Paperwork
If you are reading this right before tax night looking for a quick tax deduction, the SEP IRA takes the crown:
- SEP IRA Deadline: You can establish and fund a SEP IRA up until your tax filing deadline, including extensions (October 15 for most extended individual returns). Setup takes less than 10 minutes online, and there are no ongoing IRS reporting forms.
- Solo 401(k) Deadline: Thanks to recent legislative changes, you can set up a Solo 401(k) up to your tax filing deadline to make employer contributions. However, to make employee elective deferrals, the plan agreement generally needs to be signed by December 31 of the tax year. Once your total Solo 401(k) balance exceeds $250,000 across all accounts, you must file an annual informational return with the IRS (Form 5500-EZ).
Detailed Income Comparison: Which Saves More Tax?
To illustrate how these two accounts perform in real life, let’s examine three side hustlers with varying net profit levels from their sole proprietorship or single-member LLC.
(Assumptions for 2026: Single filer, under age 50, no full-time employees, self-employment tax deduction accounted for).
      CONTR.
     $30,000 +-------------------------------------------------------+
             |                                              $24,800  |
     $25,000 |                                            +----------+
             |                                            |          |
     $20,000 |                                            |          |
             |                                            |          |
     $15,000 |                                            |          |
             |                                            |          |
     $10,000 |                           $10,000          |          |
             |                         +----------+       |          |
      $5,000 |       $6,000            |          |       |          |
             |    +----------+         |          |       |          |
          $0 +----+----------+---------+----------+-------+----------+
                    $30k Net             $50k Net           $100k Net
                    Side Income          Side Income        Side Income

                  [  ] SEP IRA Max     [  ] Solo 401(k) Max
Scenario A: The Modest Side Hustler
- Net Side Hustle Profit: $15,000
- SEP IRA Contribution: ~$3,000 (20% of net profit after SE tax deduction)
- Solo 401(k) Contribution: ~$14,100 (100% of earned income after SE tax deduction)
- Takeaway: The Solo 401(k) allows you to shelter almost 4.5 times more income than the SEP IRA at this earnings level.
Scenario B: The Mid-Tier Freelancer
- Net Side Hustle Profit: $50,000
- SEP IRA Contribution: ~$10,000
- Solo 401(k) Contribution: ~$28,800 ($23,500 employee deferral + ~$5,300 employer profit share)
- Takeaway: The Solo 401(k) lets you put away nearly 60% of your earnings, whereas the SEP IRA caps you at 20%.
Scenario C: The High-Earning Solopreneur
- Net Side Hustle Profit: $200,000
- SEP IRA Contribution: ~$40,000
- Solo 401(k) Contribution: ~$63,500 ($23,500 employee deferral + ~$40,000 employer profit share)
- Takeaway: Even at high earnings, the Solo 401(k) retains a $23,500 edge due to the separate employee contribution component.
Crucial Warning for W-2 Employees with Side Hustles: Elective deferral limits apply per person, not per plan. If you already contribute $23,500 to a 401(k) at your full-time W-2 job, you cannot make another $23,500 employee contribution to your side hustle Solo 401(k). You can, however, still make employer profit-sharing contributions to your Solo 401(k) or use a SEP IRA.
Pros and Cons for Side Hustlers
Solo 401(k)
====================================================================
                        SOLO 401(k) SUMMARY
====================================================================
PROS:                                 CONS:
[+] Maximize savings at low income   [-] Form 5500-EZ at $250k balance
[+] Employee + Employer flexibility  [-] Harder to set up last-minute
[+] Built-in Roth options & loans     [-] No full-time employees allowed
====================================================================
Pros:
- Maximum Tax Deductions at Lower Incomes: Allows heavy front-loading of retirement savings even if your business profits are modest.
- Roth Choices: Complete access to Roth contributions for tax-free growth and withdrawals in retirement.
- Borrowing Power: Access to penalty-free loan provisions for cash flow needs.
- Spousal Inclusion: Your spouse can earn income through the business and contribute to the same plan, doubling the family maximum limit.
Cons:
- Filing Requirement: Requires filing IRS Form 5500-EZ once plan assets top $250,000.
- Employee Restrictions: You must terminate the plan or convert it to a standard 401(k) if you hire full-time employees (working 1,000+ hours per year).
SEP IRA
====================================================================
                          SEP IRA SUMMARY
====================================================================
PROS:                                 CONS:
[+] Zero annual IRS reporting         [-] Low contributions on small profit
[+] Fast & easy setup past year-end   [-] No loan options allowed
[+] Allows non-spouse employees       [-] Lower custodian Roth support
====================================================================
Pros:
- Ultimate Simplicity: Takes 5 minutes to open with no ongoing IRS tax reporting or filings.
- Flexible Contributions: No requirement to contribute every year; easily skip or adjust based on business cash flow.
- Late-Year Saver: Can be opened and funded at the absolute last minute up to your tax extension deadline.
Cons:
- Low Relative Contribution Cap for Small Earners: Capped at ~20% of net self-employment earnings.
- No Loan Access: Funds are locked up until age 59½ without incurring penalties.
- Employee Coverage Rule: Must cover eligible employees on the same percentage basis if you expand your team.
Which Account Should You Choose?
                        DECISION TREE
                        -------------

          Do you plan to hire non-spouse employees?
                           /   \
                         YES    NO
                         /       \
                        v         v
                   [SEP IRA]   Do you want to maximize savings on
                               net income under $150,000?
                                       /   \
                                     YES    NO
                                     /       \
                                    v         v
                              [Solo 401k]  Do you want zero annual IRS
                                           paperwork forever?
                                                  /   \
                                                YES    NO
                                                /       \
                                               v         v
                                          [SEP IRA]  [Solo 401k]
Choose a Solo 401(k) If:
- You want to maximize savings on income under $150,000: The employee deferral component is unmatched for small or variable side hustle profits.
- You want a Roth retirement account: You prefer paying taxes now to secure compound tax-free growth.
- You don’t plan to hire full-time staff: Your business model is strictly solo, contractor-based, or run with your spouse.
- You value access to plan loans: You want emergency access to capital without triggering taxable events.
Choose a SEP IRA If:
- You missed the December 31 deadline for employee deferrals: You need an immediate tax deduction for last year and it’s already spring.
- You hate paperwork: You do not want to monitor account thresholds or file IRS Form 5500-EZ.
- Your side hustle income is very high ($200,000+): You can already max out or reach your target savings threshold using the 20% employer contribution alone.
- You employ or plan to hire staff: You need a compliant plan that easily scales with team members.
For a deeper dive into managing cash flows between your day job and independent business ventures, read our guide on self-employed finances.
How to Set Up and Fund Your Account
Getting started is straightforward. Here is a step-by-step roadmap to establish either account:
+-----------------------------------------------------------------+
|                  ACCOUNT SETUP ROADMAP                          |
+-----------------------------------------------------------------+
| Step 1: Calculate Net Self-Employment Profit                    |
| Step 2: Obtain Employer Identification Number (EIN) from IRS    |
| Step 3: Choose Brokerage (Fidelity, Schwab, Vanguard)           |
| Step 4: Complete Adoption Agreement & Account Application       |
| Step 5: Transfer Funds & Select Investment Allocation           |
+-----------------------------------------------------------------+
- Calculate Your Net Self-Employment Profit: Review your Schedule C or business income statements.
- Obtain an EIN: While sole proprietors can open some accounts with a Social Security Number, getting a free Employer Identification Number (EIN) from IRS.gov is recommended for business isolation and security.
- Select a Custodian: Top-tier online brokerages (Fidelity, Charles Schwab, Vanguard) offer both accounts with zero setup fees, zero maintenance charges, and commission-free stock/ETF trading.
- Complete the Adoption Agreement:
- For a SEP IRA, sign IRS Form 5305-SEP (kept for your records) and complete the online application.
- For a Solo 401(k), fill out the custodian’s plan adoption agreement and name your plan (e.g., “Apex Marketing Solo 401(k) Plan”).
- Deposit Funds and Invest: Transfer money directly from your business bank account. Remember to select investments (such as low-cost index funds or target-date funds) after the cash clears.
To learn more about optimizing your deductions and tracking business expenses cleanly, check out our resource on tax strategies for side hustlers.
Common Mistakes Side Hustlers Make
- Overcontributing Across Multiple 401(k)s: Forgetting that your W-2 job’s 401(k) contributions count toward your $23,500 individual employee deferral limit.
- Leaving Cash Uninvested: Depositing money into the retirement account but leaving it in a 0% interest sweep account rather than purchasing index funds or stock assets.
- Forgetting Form 5500-EZ: Missing the mandatory IRS filing once your Solo 401(k) assets surpass $250,000 at year-end.
- Confusing Gross Income with Net Income: Base your math on net self-employment earnings (gross revenue minus business expenses minus half of self-employment tax), not top-line revenue.
If you are currently evaluating options to scale your online revenues, explore our latest strategies for generating side hustle income.
Essential External Resources
To ensure you stay compliant with official tax codes and regulations, refer to these authoritative references:
- IRS Publication 560: Retirement Plans for Small Business – Official guidance on SEP, SIMPLE, and Qualified Plans.
- IRS One-Participant 401(k) Plans Guide – Rules, limits, and filing requirements for Solo 401(k)s.
- Department of Labor Form 5500 Corner – Instructions and threshold guidelines for annual plan filings.
Take Action on Your Self-Employed Future
When comparing the Solo 401(k) vs SEP IRA for side hustlers, the Solo 401(k) emerges as the winner for most solo operators. Its ability to combine employee deferrals with employer profit sharing allows you to shelter far more income at modest earning levels, while offering Roth flexibility and loan provisions.
However, if you want zero ongoing administrative responsibilities or need to secure a tax deduction after December 31, the SEP IRA remains an extraordinarily effective alternative.
The most critical step isn’t finding the mathematically perfect plan—it is taking action. Every month you delay is a month of missed compound growth and lost tax savings. Evaluate your current income level, decide on your ideal account type, open your plan with a reputable broker, and start automating your self-employed retirement contributions today.

Want to Make Money From Home ?
Join 55,000+ real, remote ways to make money every week.
Good luck! I hope you find the perfect remote opportunity for your lifestyle and goals.
Disclaimer: This article is intended solely for educational and informational purposes and does not constitute personalized financial, legal, or investment advice. Always consult with a qualified financial advisor or non-profit credit counselor regarding your specific situation.